
The semiconductor has become the first technology in history to be governed like oil. Export controls — once the obscure machinery of arms regulation — now decide which countries’ companies may buy which chips, which tools may be sold to make them, and which engineers may work where. The chip map is being redrawn in real time by a contest between the United States and China, with every other technology economy — Europe, Japan, Korea, Taiwan, India — positioning on the new terrain. The industry’s founding assumption, that chips were a global business, is being revised by governments that now file them under national survival.
The controls work through chokepoints, and the industry’s geography is made of them. A single Dutch company builds the lithography machines every advanced chip requires; a single Taiwanese giant fabricates most of the world’s leading-edge logic; American firms dominate the design software. Export rules aimed at these narrow points can slow a rival’s entire AI programme — which is precisely what they are designed to do, as their architects state with unusual candour. Readers can follow more coverage like this on techdaytimes.com.
The Subsidy Race Answers
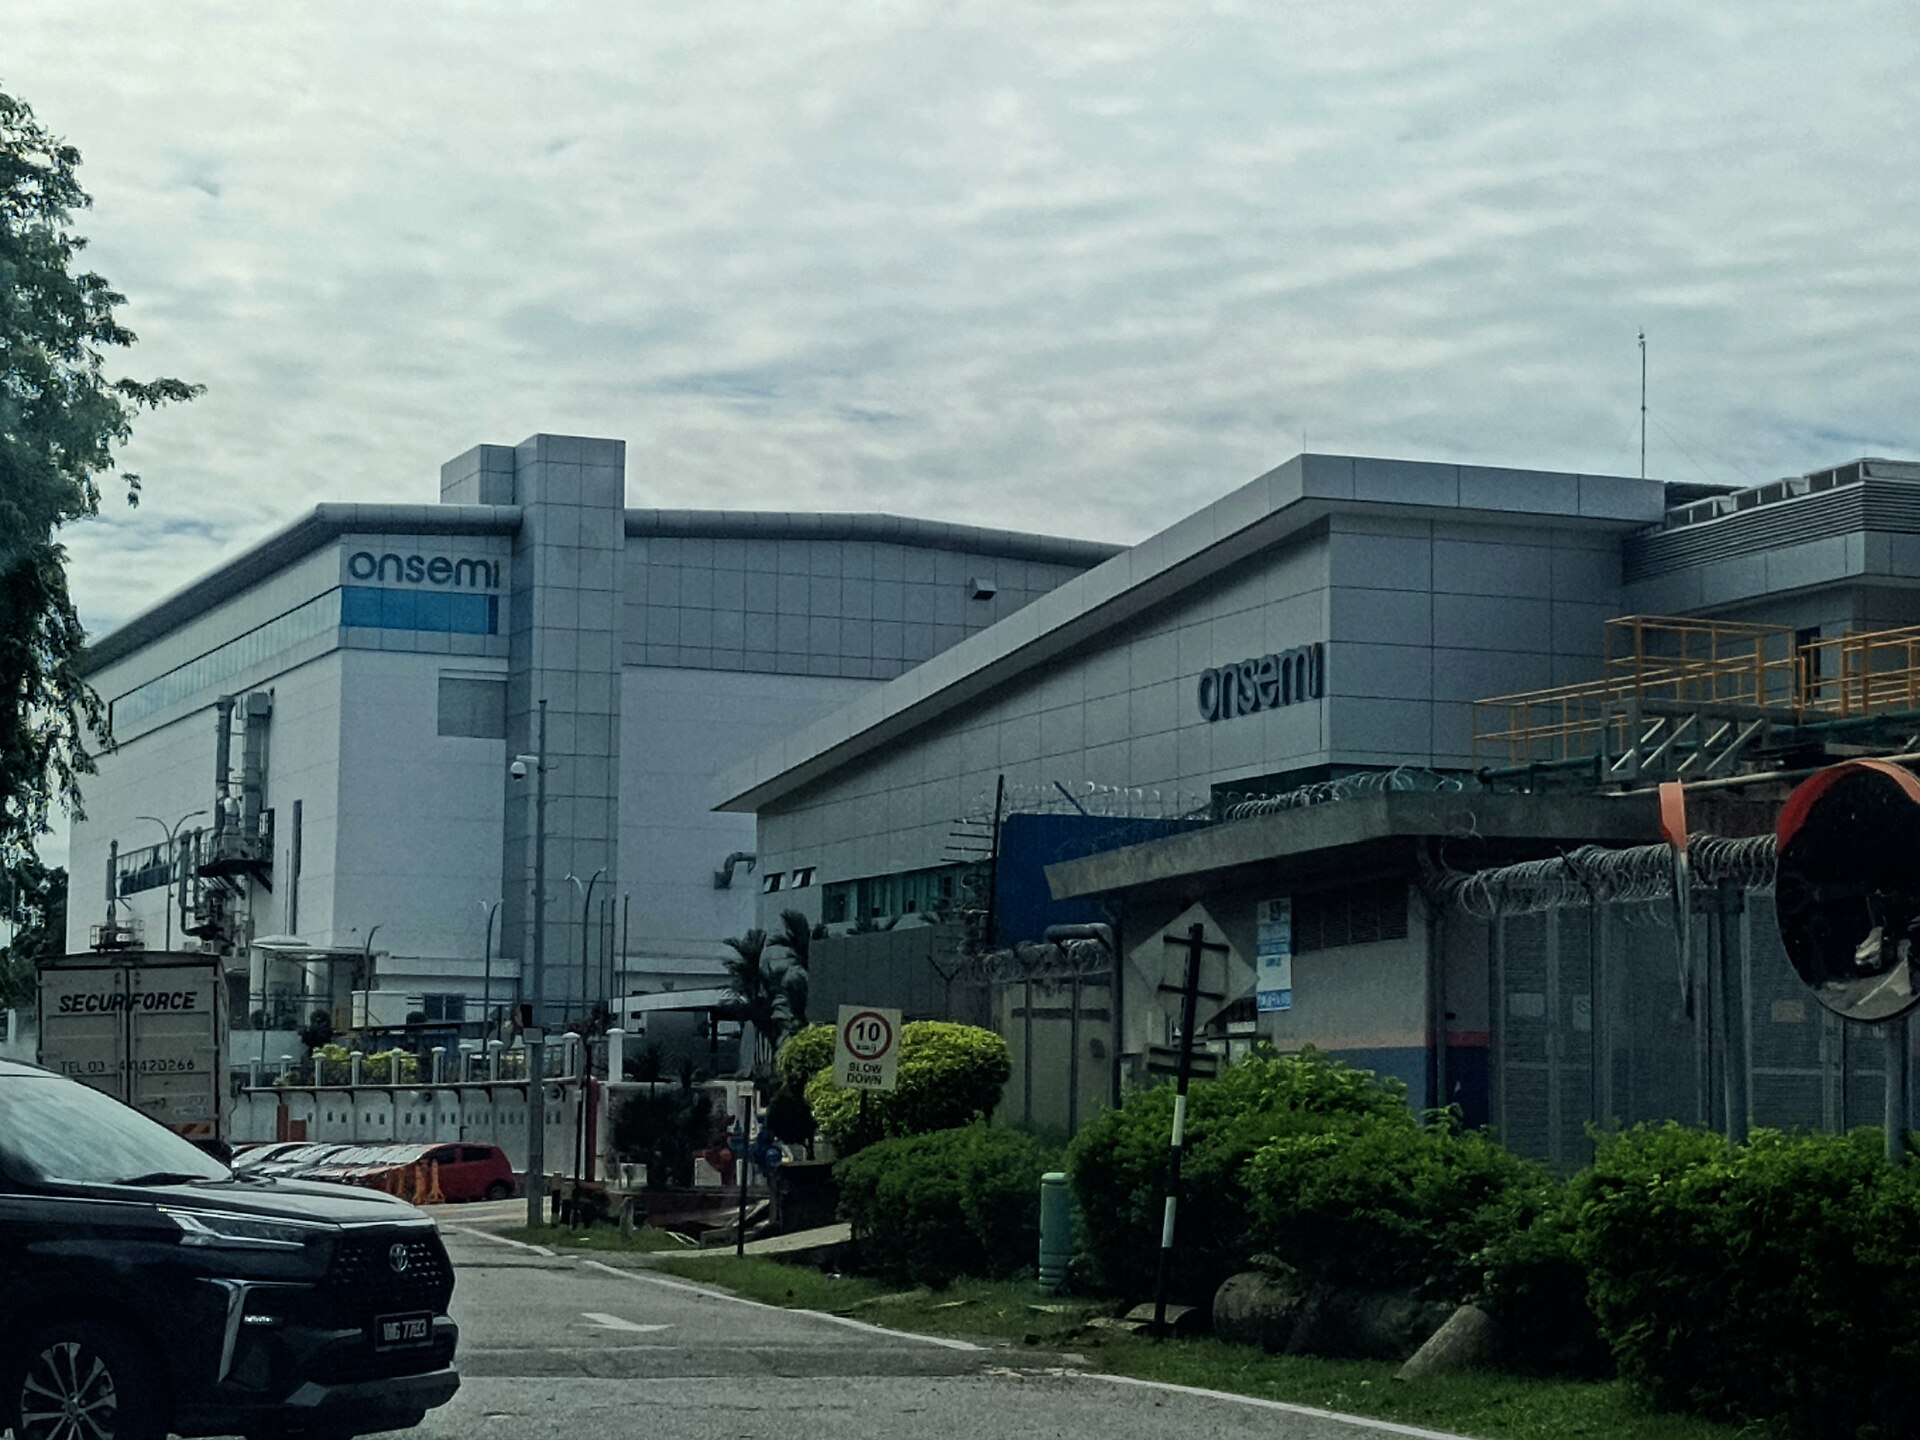
Every major economy has responded with industrial policy on a scale not seen in generations: tens of billions in subsidies for fabrication on home soil, from the American CHIPS Act to the European and Japanese and Indian equivalents. The new fabs rising in Arizona, Saxony, Kumamoto and Gujarat are therefore strategic assets first and businesses second — their economics argued in the language of resilience: what share of a critical input a nation can survive being cut off from, priced against the efficiency the global system achieved by concentrating production where it was cheapest.
The honest arithmetic is uncomfortable for everyone. Duplicated supply chains cost more — chips from the new subsidised fabs carry a premium over the incumbent’s — and no country, including the largest, can replicate the full stack alone: the map is being redrawn toward trusted blocs rather than autarkies, allied shoring rather than home shoring. Companies navigate with multi-track strategies, designing products that can be made in several jurisdictions and lobbying, in public, for predictability above generosity.
The Evasion and the Escalation
Controls breed circumvention — third-country transshipment, cloud access to restricted computing, domestic substitution efforts that progress faster than the controllers forecast — and each round of leakage has produced a wider round of rules. China’s counter-moves write the other half of the spiral: export licences on the rare earths and minerals the chip industry itself consumes, investment in a parallel equipment ecosystem, and a state commitment to the problem measured in decades. The contest’s centre of gravity is shifting from the chips themselves to the machinery and materials beneath them. Further data and analysis on this subject are available from the Center for Strategic and International Studies.
For the rest of the world the age of picking technology off a global shelf is ending in the strategic layers while continuing in the ordinary ones — your appliances will not lack for microcontrollers even as the frontier AI accelerators become diplomatic instruments. Companies describe the resulting world with a phrase that has entered the boardroom lexicon: one world for commerce, another for capability, and a border that compliance departments now patrol.
The Map Being Drawn
The industry’s own mapmakers — the equipment makers and foundries — have become diplomats by necessity, maintaining engineering centres and customer rosters across the dividing lines and testifying, carefully, in everyone’s capital.
Maps of this kind, once drawn, persist for generations — the oil map outlived the century that drew it. The chip map’s lines are being set now, in legislation and fab groundbreakings, by officials who know they are deciding where the twenty-first century’s commanding technology will be allowed to live. The fabs take years, the ecosystems decades. What is being allocated, in the meantime, is the future’s geography — one export licence at a time. See also our companion piece: Sodium-Ion Batteries: The Cheap Chemistry Coming for Lithium’s Lunch.
